
Sunbit
- Rating
- 3.9
- Downloads
- 500.00K
- Content Rating
- Everyone
Sunbit - Screenshots
Pros
- Quick approval process with a soft credit check for many applicants.
- Payment plans can make unexpected purchases easier to manage.
- Available at participating retailers
- clinics
- and automotive service locations.
- Application is completed digitally with minimal paperwork.
- No interest is charged when payments are made on time under the plan terms.
Cons
- Sunbit is only available through selected partner merchants.
- Late or missed payments may lead to fees or credit reporting.
- Approval
- spending limits
- and terms depend on your credit profile.
- Not every purchase or service qualifies for Sunbit financing.
- Some plans may carry a high effective cost compared with other options.
Sunbit - Description
- App Name
- Sunbit
- Package Name
- com.mysunbitnative
- Developer
- Sunbit
- Category
- Finance
- Last Updated
- May 23, 2021
- Version
- 2.6.37
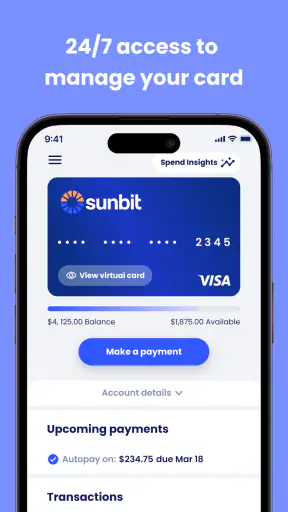
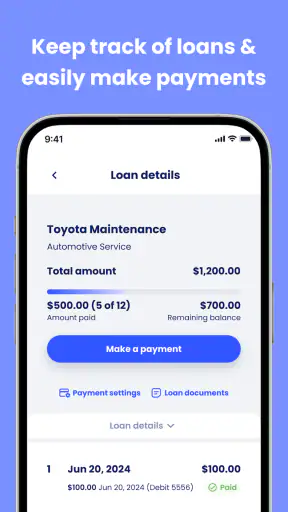
I approached Sunbit as a practical finance app rather than something I would open every day for entertainment. Its purpose is focused: it lets me manage a Sunbit Card and payment plans from a phone. That narrow focus is important because the experience makes the most sense for someone who already uses Sunbit and wants a simpler way to keep an eye on payments while away from a computer.
Sunbit is free, aimed at everyone, and developed by Sunbit. It belongs to the personal finance category, has passed half a million installs, and holds an average rating of 3.9 from roughly 1,400 ratings. Those figures suggest a reasonably established app, although they also tell me to expect a useful account-management tool rather than a flawless replacement for every banking service.
My main question while using it was not whether it could do everything a full banking app does. It clearly has a more specific job. The better question is whether that job is presented clearly enough for people with different reading, movement, attention, and situational needs. In my experience, the answer is mostly positive, but the app’s usefulness depends heavily on the user already understanding the Sunbit relationship behind it.
How the app feels to read and navigate
The strongest part of a focused finance app is usually its limited scope, and that is also the first advantage I noticed here. When an app is built around a card and payment plans, I do not have to sort through investment tools, budgeting dashboards, transfers, insurance products, or unrelated financial promotions. That reduced choice can make the first visit less intimidating, especially for someone who wants to check one obligation quickly.
I find this kind of focused layout easier to approach than a broad financial-services app. A person who is anxious about a payment does not necessarily want a dense overview of their entire financial life. They want to know what account or plan they are looking at and what action is available next. Sunbit’s purpose supports that direct style, even though the exact ease of each screen can depend on the account state and the task being attempted.
Readability matters more in finance than it does in many other categories. A missed digit, unclear label, or rushed confirmation can lead to a very different result from a missed detail in a social app. I would therefore recommend opening the app when you have enough time to read the account information carefully instead of treating it like a notification you can dismiss in a hurry.
One useful habit is to separate checking from acting. I would first open the relevant card or plan, read the displayed information, and only then decide whether to continue with a payment-related action. This two-step pause is especially helpful for people who find financial language tiring or who need extra time to process numbers. It also reduces the chance of tapping through a screen simply because the next button is visually prominent.
For users with low vision, the phone’s own text enlargement, display scaling, contrast, and screen-reader settings may make a meaningful difference. I would not assume that every label becomes equally comfortable at larger sizes, so I would test the important screens before relying on the app for an urgent payment. The practical test is simple: can you identify the card or plan, understand the amount and timing, and locate the next action without guessing?
That test is more valuable than judging the app by its opening screen. Finance interfaces can feel clear when browsing and become harder when a user reaches a confirmation, account-verification, or error state. I would pay particular attention to those moments because they are where a person needs the most confidence and the least ambiguity.
Navigation that works best for focused tasks
Sunbit suits short, purposeful visits. I can imagine opening it to check a plan before making a purchase decision, confirm what I need to handle next, or review card-related information while away from home. It is less suited to someone who wants a single place for several unrelated accounts, because its value comes from staying close to Sunbit rather than becoming a complete financial command center.
The app’s current version is 2.6.37, and it runs on Android 8.0 or later. That gives it a reasonably broad Android range, which is useful for people who keep an older phone because replacing a device is expensive or inconvenient. Still, supporting an older operating system does not automatically mean that every older device will offer the same speed, display quality, or input comfort. A slower phone can make a short finance task feel much more stressful.
If you are helping a family member use the app, I would avoid taking over the entire process. Instead, ask the person to identify the card or plan they intend to manage, then let them confirm the important details themselves. This approach supports independence and catches misunderstandings earlier than simply completing every tap for them.
Motor, sensory, and cognitive considerations
Touch-based finance apps can be demanding for people with tremors, limited dexterity, reduced sensation, or difficulty making precise taps. A payment-related action should never depend on a hurried swipe or a tiny control that is easy to hit accidentally. My practical advice is to use a stable surface, increase touch-and-hold timing through the phone’s accessibility settings when needed, and avoid operating the app while walking or carrying something.
Voice control can also help users who struggle with repeated tapping, but I would treat it as an assistive layer rather than a guarantee that every task can be completed hands-free. Financial actions often require visual confirmation, and I would still inspect the final details on screen before approving anything. That is not an inconvenience unique to Sunbit; it is a sensible safeguard whenever money is involved.
Sensory load is another consideration. People who are sensitive to bright screens, motion, or visual clutter may prefer using the app with reduced brightness, a calmer display setting, or the phone’s reduced-motion options if available. I would also silence unrelated notifications during a payment check. The goal is to make the financial task the only thing competing for attention.
Cognitive accessibility is particularly important here. Payment plans can involve dates, amounts, and conditions that are easy to confuse when someone is tired, stressed, or managing several responsibilities. I would write down the specific question I want answered before opening Sunbit. For example, I might note, “I need to check the next amount connected to this plan,” rather than entering the app with a vague intention to “look at finances.” A defined goal makes the session shorter and lowers the mental load.
Another useful technique is to review one plan at a time. If several items appear in the account, I would not compare them from memory. I would read the identifying information, pause, and record only what matters for the decision in front of me. This is a small workflow change, but it can help users with attention difficulties, dyscalculia, or financial anxiety avoid mixing up similar-looking obligations.
For people who rely on captions or visual alternatives, the app’s finance-focused nature means that most important information is likely to be text or numbers rather than spoken media. That can be helpful in noisy environments, but it also means that text clarity carries much of the experience. I would not use a busy café, a moving vehicle, or a poorly lit room as the place to learn the interface for the first time.
A realistic everyday situation
Imagine that I am at a participating retailer and considering whether to use my Sunbit Card or an existing payment plan. I could open the app before reaching the checkout, review the relevant information, and make sure I understand what I am looking at while I still have time to concentrate. If I waited until a queue was moving quickly, with people behind me and a cashier waiting, the same task could feel much harder.
For a user with hearing loss, that preparation also reduces dependence on spoken explanations at the counter. For someone with limited mobility, it may avoid repeated movement between the checkout and another place where account information is stored. For someone with anxiety, it creates a quieter moment to read instead of making a financial decision under social pressure.
The trade-off is that the app does not remove the need for judgment. It can put account and plan management within reach, but I still need to understand the information and choose carefully. That distinction matters: convenient access is not the same as financial advice, and a clear screen cannot decide whether a payment arrangement is suitable for my budget.
Where situational access makes a difference
I think Sunbit is most useful when access to a larger screen is inconvenient. A phone is easier to carry into a store, keep beside me at home, or use while coordinating a purchase with another person. That portability can benefit users who cannot easily reach a desktop computer, people who travel between locations, and anyone who needs to check a plan without searching through paper records.
It can also support people who share responsibilities with a trusted helper. A family member might sit beside the account holder while they review the information together. I would keep the account holder involved in every important decision, because accessibility should increase control rather than quietly transfer it to someone else.
Connectivity and surroundings still matter. A phone in a basement, crowded shop, or area with unreliable service may not be the ideal place to complete a time-sensitive task. I would check important information before leaving a reliable connection and avoid assuming that a screen will behave exactly the same way in every environment. A small amount of preparation can prevent a stressful interruption.
Older Android users may appreciate that the app supports Android 8.0 and newer. That does not mean every older handset will feel equally responsive, but it does make the app more approachable for people who are not using a recent flagship phone. If your device has a small display, weak battery, or a damaged touchscreen, however, the physical phone may become the main accessibility barrier rather than the app itself.
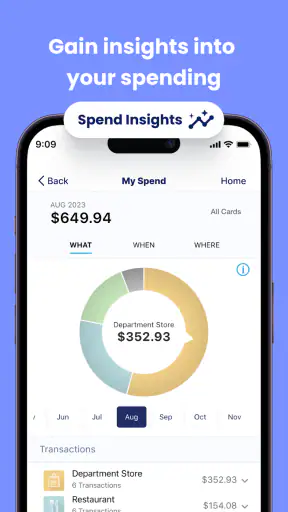
The app is also a better fit for users whose needs are tied specifically to Sunbit. Someone looking for broad expense tracking, multiple bank connections, detailed budgeting, or a general credit-management workspace would probably find a conventional banking or budgeting app more appropriate. Those alternatives may offer a wider financial picture, while Sunbit’s advantage is staying focused on its own card and payment-plan relationship.
Remaining barriers and sensible precautions
The biggest limitation is scope. I would not install Sunbit expecting it to replace my primary bank app. Its role is narrower, so users who want consolidated accounts or comprehensive financial planning may end up switching between several apps. That is not necessarily poor design, but it does create extra mental work for people who already struggle with fragmented information.
A second barrier is the seriousness of the tasks involved. Even a well-organized interface can be difficult when a user is worried about money. I would avoid completing a payment action while distracted, and I would not rely on memory for dates or amounts. Reading the final screen aloud, enlarging the display, or asking a trusted person to verify what is visible can be sensible accommodations, provided the account holder remains the final decision-maker.
People with motor impairments should consider how much precision the phone requires in their own setup. A stylus, a phone stand, an adaptive switch, or voice access may help, but the best option depends on the individual and the device. I would test these tools on harmless navigation first rather than introducing them for the first time during an important financial action.
People with cognitive disabilities may benefit from a written routine: open the app, select the intended card or plan, read the key information, pause, and confirm only after checking the purpose of the action. Keeping that routine beside the phone can be more effective than trying to remember a complicated sequence under pressure.
I would also be cautious about shared phones. A convenient mobile account-management app becomes less private when other people regularly use the same device. Use the phone’s own security and account-protection settings, and make sure you understand who can see the screen before opening financial information in public or around visitors.
The rating of 3.9 shows that the experience is useful for many people but not universally smooth. I read that as a reason to test the app with my actual phone, display settings, and account needs rather than assuming that another person’s experience will match mine. The app is free to install, but the financial decisions managed through it are obviously not casual ones; convenience should never be confused with affordability.
My inclusive verdict
Sunbit is a sensible choice for someone who already uses Sunbit and wants mobile access to the related card and payment plans. I like its focused purpose, its suitability for short account checks, and the way a phone can make this information available in places where a computer is impractical. Its support for Android 8.0 and later also gives people with older devices a fair chance to try it.
From an inclusion perspective, the app works best when combined with the phone’s accessibility settings and a deliberate personal routine. Larger text, reduced distractions, voice assistance, a stable setup, and a trusted helper can make the experience more manageable for different abilities and circumstances. I would still test the important screens personally, because accessibility is not identical for someone with low vision, limited dexterity, hearing loss, memory difficulties, or financial anxiety.
I would skip it if I wanted a complete budgeting platform, a consolidated view of several financial providers, or guidance about whether a payment arrangement fits my situation. A broader finance app would be a better companion for those needs. I would also avoid making it my only plan for urgent account access until I had confirmed that it works comfortably on my phone and in the environments where I expect to use it.
Overall, I see Sunbit as a practical specialist tool rather than an all-purpose money manager. Its best quality is that it brings a specific card-and-plan task onto a portable screen without asking users to navigate an entire banking ecosystem. My recommendation is to use it as a prepared, careful way to manage Sunbit information—not as a substitute for reading the details, protecting your privacy, or making an independent financial decision.
FAQ
What is Sunbit, and how does the app work?
Sunbit is a financial technology app and payment service designed to help users apply for installment financing when purchasing products or services from participating merchants. Depending on eligibility, users may be able to view payment options, complete an application, and manage an existing plan. Availability, loan terms, and supported merchants can vary, so it is important to review the offer details before accepting.
Does using Sunbit affect my credit score?
Sunbit may use information from your application to assess eligibility, and the type of credit inquiry can depend on the stage of the application and the product offered. Users should carefully read the disclosures shown in the app or at checkout to understand whether a credit check is involved and how it may be reported. Approval is not guaranteed, and terms differ by applicant.
What fees and interest charges can Sunbit include?
The cost of a Sunbit payment plan depends on factors such as the purchase amount, repayment period, applicant profile, and applicable merchant or lender terms. Some offers may include interest, while other costs or conditions may apply. Before confirming, check the annual percentage rate, total repayment amount, installment schedule, late-payment policy, and any other fees displayed in the agreement.
Is Sunbit safe to use for payments and personal information?
Sunbit is intended to process financing applications and payments through secure digital systems, but users should still take normal precautions. Download the app from an official store, verify that communications come from legitimate Sunbit channels, and avoid sharing login details or verification codes. Review the privacy policy to understand how personal, financial, and transaction information is collected and used.
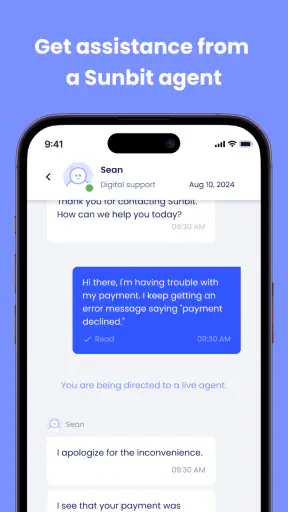
What happens if I miss a Sunbit payment or need to cancel a purchase?
Missing a payment may result in consequences described in your financing agreement, such as late fees, account restrictions, or possible effects on credit reporting. If you return an item or cancel a service, the merchant generally handles the purchase dispute or refund, while Sunbit manages the financing balance according to its policies. Contact both the merchant and Sunbit support promptly for clarification.


